US equities edged higher on Monday ahead of the July 4th public holiday, shrugging of data that showed a slowdown in manufacturing by more than expected.
United States
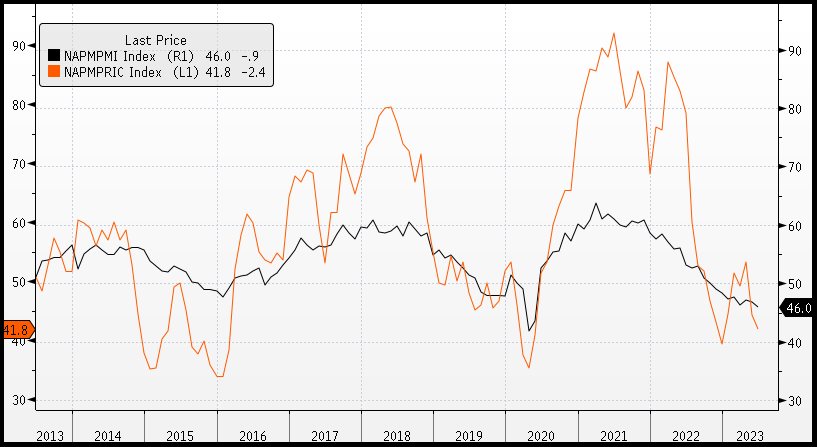
Economic data on Monday revealed a less optimistic view of the US economy, with the ISM manufacturing PMI dropping to the lowest level in three years from 46.9 in May to 46 in June, while estimates had called for a modest increase. In a further encouraging sign for the easing in inflationary pressures, the sub-index of prices paid declined more than forecast to 41.8 from 44.2 previously, with both employment and new orders also declining. Attention for the remainder of the week turns to the release of the latest FOMC policy minutes on Thursday, followed by non-farm payroll data on Friday.
US ISM Manufacturing PMI (MoM)
The S&P 500 closed slightly higher, rising by 0.12%. Consumer discretionary was up by 1.07%, real estate added 0.85% while consumer staples firmed up 0.69% while healthcare and information technology were the biggest laggards, sliding -0.82% and -0.31% respectively. The Dow Jones edged up 0.03%, the Nasdaq Composite advanced 0.21% while the Russell 2000 Index gained 0.43% with the VIX edged -0.15% lower to 13.57.
Europe
In Europe, equities posted modest losses on Monday with little economic data to guide investors. The STOXX 600 Index declined -0.13%, despite seven out of the eleven sectors closing in the green, with the index weighed down by healthcare which sank -1.94%, industrials declined by -0.67% and consumer discretionary lost -0.61%. The CAC fell -0.18%, the DAX lost -0.41%, while the FTSE edged -0.06% lower.
*Note: These prices are based on futures and/or CFD pricing and may therefore differ slightly from spot pricing.
Australia
The highly anticipated RBA decision is on the radar today with financial markets betting on interest rates remaining unchanged at 4.1%, implying a 80% probability based on RBA cash rate futures while economist forecasts as split between a hike or pause. Should the central bank indeed pause today, expectations are that this would be followed by a further increase in August, unless we see significant progress on the inflation front or weakening economic data. Commonwealth Bank’s Harry Otley shared his views, adding, “The deceleration in the monthly CPI should be enough for the RBA to pause its hiking cycle. Although today’s stronger housing related data could, together with a tight labour market and lingering inflation concerns, tip the decision the other way.”
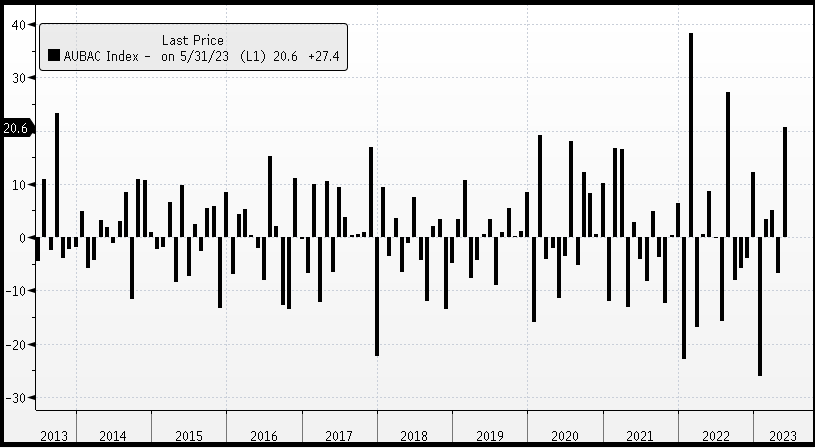
Economic data on Monday supported the recent rise in housing prices, with loans increasing up by 4.8% in May while building approvals jumped 20.6% well above estimates of 2%. The ASX is set to open flat today with ASX futures little changed at 7,216. The index gained 0.59% on Monday to close at 7246 with shares in United Malt a notable performer, rising 8.6% after saying it reached an agreement with Malteries Soufflet of France for a $5 per share takeover. In materials, Silver Lake Resources rocketed 7.77%, Bellevue Gold jumped 4.33%, Pilbara Minerals advanced 3.48%, Lake Resources firmed 3.33% and South 32 added 1.33%. WiseTech was the biggest underperformer, sliding -2.94% after shares have risen 56% in 2023. The Australian dollar was modestly higher on Monday at 0.6673 while the policy-sensitive 3-year bond yield declined -8.8 basis points to 4.26%.
Australian Building Permits (MoM %)
Commodities
Oil prices declined despite Saudia Arabia announcing a prolonged cut in production of oil by another month. WTI and Brent crude fell -1.20% and -0.60% to $69.79 and $74.96 respectively. The price of spot gold rose by 0.12% to $1,921, while spot silver advanced 0.63% to $22.92. Industrial metals mixed with copper, rising 1.02% to $378, while SGX Iron Ore prices weakened by -0.61% although is 0.45% higher this morning at US$108.90.
Economic Calendar
4th July 2023
RBA Rate Decision 14:30
This article was written by James Woods, Portfolio Manager, Rivkin Securities Pty Ltd. Enquiries can be made via [email protected] or by phoning +612 8302 3632.

