US equities started the week on a positive note as investors await key economic data and the bulk of company earnings reports.
United States
Companies with a combined value of $27 trillion are expected to share their results this week, including Apple, Google, Microsoft Corp., LVMH and Samsung Electronics. Chief Investment Officer at Main Street Research, James Demmert commented, “We expect big tech earnings to be mixed and the real test will be for companies that have significant exposure to artificial intelligence as investors are eager to see if these companies can report strong enough results to support their significantly elevated share prices in recent months”. Investors await the Fed’s meeting on Wednesday, where the central bank is expected to raise the cash rate by a quarter of a percentage point.
Meanwhile, PMI data released on Monday pointed to an improved outlook, although we continue to see a divergence between the strength of manufacturing and services. Manufacturing PMI unexpectedly improved in July to 49 compared to estimates to remain little changed at 46.2 with the gauge now modestly below the 50 level which signals contraction or expansion. Meanwhile, services PMI was slightly softer than expected at 52.4 vs 54 estimated. The data adds weight to the recent strength of the US economy, highlighted by the Citi Group US Economic Surprise index which has risen strongly over the past year.
Eurozone Economic Suprise Index
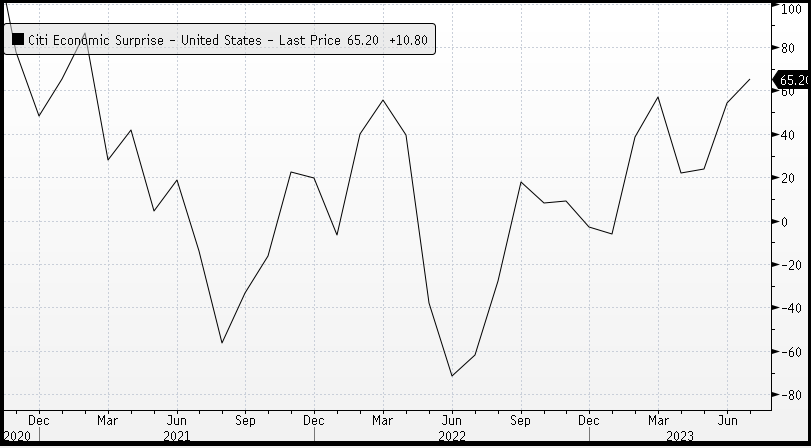
The S&P 500 closed 0.40% along with the Dow Jones 0.52%, Nasdaq Composite 0.19% and Russell 2000 0.28% with the VIX rising 2.28% to 13.91 The yield on the 2-Year treasury bond rose by 7 basis points to 4.92%, while the yield on the 10-Year treasury bond climbed 3 basis points to 3.87%.
Europe
In Europe, PMI reports also highlighted the divergence between strength in the services and manufacturing sectors. Manufacturing PMI declined to 42.7 in July, below estimates of 43.5 while services PMI remained in expansionary territory with a reading of 51.1. Compared to the United States, Eurozone economic data continues to surprise to the downside, pointing to a weaker outlook for economic growth. This is highlighted by a significant decline over the past 12 months in the Citi Group Eurozone economic surprise index.
Eurozone Economic Suprise Index
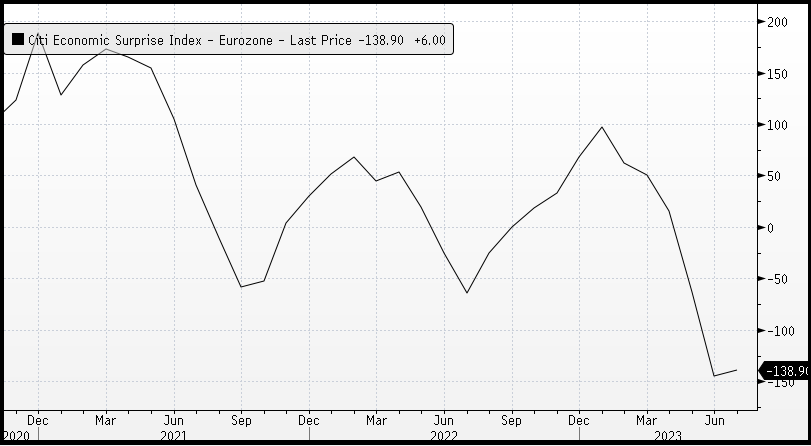
Major equity benchmarks were mixed with the Euro Stoxx 600 edging 0.06% higher along with the DAX 0.08% and FTSE100 0.19% while the CAC edged -0.07% lower. Investor focus will be on the upcoming ECB and Fed meetings over the next few days, where both banks are expected to announce rate hikes while keeping one eye on corporate earnings.
*Note: These prices are based on futures and/or CFD pricing and may therefore differ slightly from spot pricing.
Australia
The ASX 200 Index is expected to open higher today, with ASX futures up 0.56% to 7,301. The index closed -0.10% lower at 7306, despite the majority of sectors ending the trading session in green. The index was weighed down by the materials sector dropping -1.41%. Lake Resources lost -5.88% along with Pilbara Minerals -5.75% following a decline in Chinese lithium prices and lower production guidance from miner Core Lithium weighing on the sector. Lithium explorer Core Lithium was the biggest underperformer of the index, plummeting -17.2% after announcing a decline in production for the year ending June 2025, compared to 2024. Paladin sank -5.75%, Syrah Resources receded -2.72%, BHP and RIO declined -1.51% and -1.31% respectively. The big bank’s share prices dropped, namely NAB, ANZ, CBA & Westpac in the range between -0.09% to -0.75%.
In economic data, both manufacturing and services PMI reports for July are modestly in contractionary territory, with manufacturing rising to 49.6 from 48.2 previously while services weakened to 48 from 50.3. The Australian dollar is modestly higher overnight by 0.15% to 0.6739 while the yield on 3-year government bonds was -3 basis points lower at 3.916%.
Commodities
Oil prices soared on Monday. The price of WTI and Brent Crude was up by 2.17% and 2.10% to $78.74 and $82.77 respectively. In precious metals, the price of spot gold fell by -0.37% to $1,954 while the price of spot silver slid -0.03% to $24.34. Industrial metals were with copper advancing 0.99% to $384, while SGX Iron Ore declined by -0.91% to $112.63. The price of Bitcoin dropped by -3.8% to $29,090.
Economic Calendar
25th July 2023
German Ifo Business Climate (MoM Jul) 18:00
US House Price Index (MoM May) 23:00
US CB Consumer Confidence (MoM Jul) 00:00
This article was written by James Woods, Portfolio Manager, Rivkin Securities Pty Ltd. Enquiries can be made via [email protected] or by phoning +612 8302 3632.

