US equities closed higher with yields lower on Tuesday, despite comments from Fed officials pushing back against easing yields.
United States
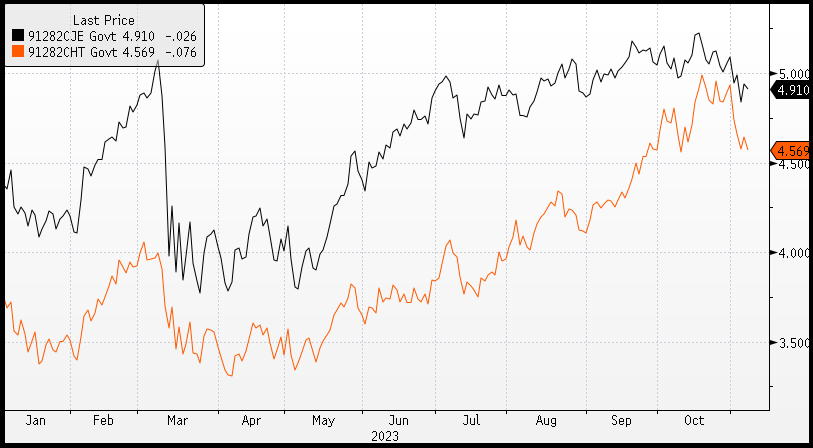
Following a fall in Treasury yields over the past week, Fed Governor Michelle Bowman said she believes the central bank will need to increase interest rates further to contain inflation, although prior tightening, which has begun to reverse, had done much of the Fed’s work for them. Elsewhere, Minneapolis President Neel Kashkari said he believes policymakers are yet to win the fight against inflation and would consider further tightening if needed. Adding to this, Chicago Fed President Austan Goolsbee said officials don’t want to “pre-commit” to decisions on rates. Tonight, a speech by Fed Chair Jerome Powell will be the highlight, scheduled for 01:15 AEDT.
Despite these comments, yields across the Treasury curve were lower, with the 2-year rate down -2.3 basis points along with the 10 and 30-year rates by -7.27and -7.9 basis points respectively. The decline in yields boosted growth stocks, with the Nasdaq Composite outperforming, up 0.90% followed by the S&P500 0.28% and Dow Jones 0.17% while the Russell 200 was -0.28% lower.
Treasury Yields
Europe
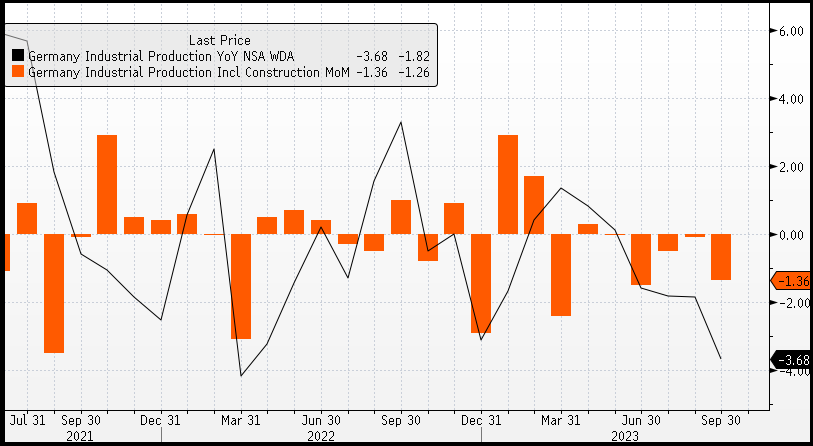
European equities finished lower on Tuesday, weighed by weaker German industrial output which declined by for a fourth consecutive month in September, decreasing -1.4% well below the -0.1% forecast. The Euro Stoxx 600 declined -0.16% along with the CAC -0.39% and FTSE100 -0.10% while the DAX rose 0.11%. A bright spot was UBS, which rose 1.83% in Zurich after reporting stronger-than-expected inflows into its wealth management business of $22 billion vs $14 billion estimated. The bank posted a net loss of $785 million for the three months to September following $2 billion in costs to absorb Credit Suisse.
German Industrial Production
Earnings season continues to roll out across the region, which compared to US results has been relatively disappointing as only 51% of companies have topped earning expectations, while aggregate earnings have missed estimates by -7.05%. Later today, Eurozone retail sales for the year to September will be released expected to show a -3.1% drop over the year and -0.2% decrease over the month.
Australia
The local market is expected to open flat this morning, with ASX200 futures -1 point lower at 6,989. The index declined -0.29% on Tuesday, paring back losses of up to -0.65% after the Reserve Bank of Australia raised interest rates by 0.25% to 4.35%, the highest level in 12 years. Despite the increase in rates, investors were focused on what was a softening in the language in the statement accompanying the decision. The statement noted “Whether further tightening of monetary policy is required to ensure that inflation returns to target in a reasonable timeframe will depend upon the data and the evolving assessment of risks”, signaling the likelihood that the central bank will soon join global counterparts in reaching a peak in the current cycle – pending no resurgence in inflation. In reaction, the Australian Dollar weakened -0.83% to 0.6435 while the policy-sensitive 3-year bond yield was -2.5 basis points lower at 4.243%.
Commodities
In commodities, oil prices plummeted upon the release of disappointing trade data out of China. WTI and Brent Crude were down by -4.26% and -4.13% to $77.38 and $81.66 respectively. Data from China on Tuesday showed exports dropped -6.4% vs -3.5% forecasts while imports rose just 3% in October. In precious metals, spot gold was down -0.53% to $1,967.67 while spot silver declined by -1.90% to $22.59. Copper shed -0.95% to $368.35 while SGX Iron Ore lost -0.59% and is a further -1.06% lower this morning at US$121.75.
Economic Calendar
8th November 2023
Eurozone Retail Sales (MoM Sep) 21:00
Fed Cook Speech 21:15
Fed Chair Powell Speech 01:15
Fed Williams Speech 05:40
Fed Barr Speech 06:00
Fed Jefferson Speech 08:45
This article was written by James Woods, Portfolio Manager, Rivkin Securities Pty Ltd. Enquiries can be made via [email protected] or by phoning +612 8302 3632.

