Equities closed higher while yields on treasuries remained relatively stable at the end of trading on Tuesday as the S&P500 posted a third consecutive month of losses.
United States
The S&P 500 climbed 0.65% overnight with all the sectors closing in the green. Real estate, financials and utilities were the star performers, rallying 2.03%, 1.10%, and 0.86% respectively. The Dow Jones edged up 0.38%, the Nasdaq Composite closed 0.48% higher, while Russell 2000 Index gained 0.91% with the VIX retreating -8.15% to 18.14.
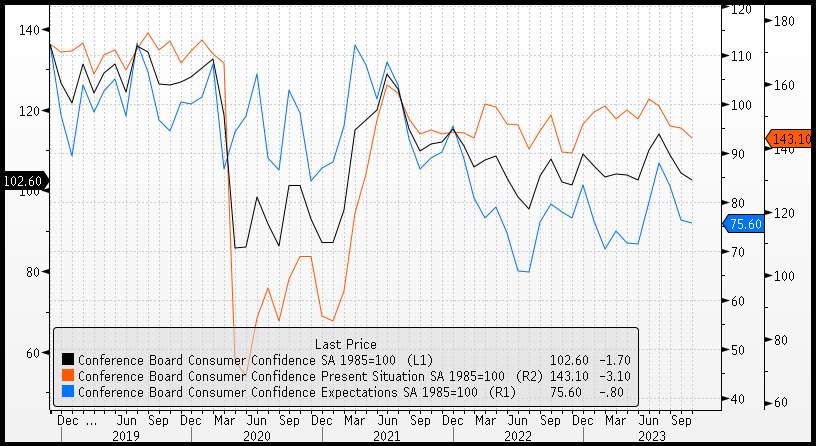
Economic data overnight showed US consumer confidence fell to a five-month low in October, although was higher than estimated. The Conference Board’s measure declined to 102.6 in October from 103 in September, while economists had forecast a lower reading of 100.5. The sub-component of the present situation deteriorated, although there was an uptick in future expectations, pointing to a more optimistic outlook amid recent strength in economic growth. Meanwhile, employment costs rose by 1.1%, marginally above estimates. Aside from the continued release of earnings reports, in the spotlight today is the Fed’s interest rate decision, forecast to remain unchanged at 5.5%. Further data includes the MBA Mortgage applications report to assess the country’s housing market, the ADP Employment change to gauge the strength of the labor force, as well as ISM manufacturing PMI.
US Consumer Confidence (MoM)
Europe
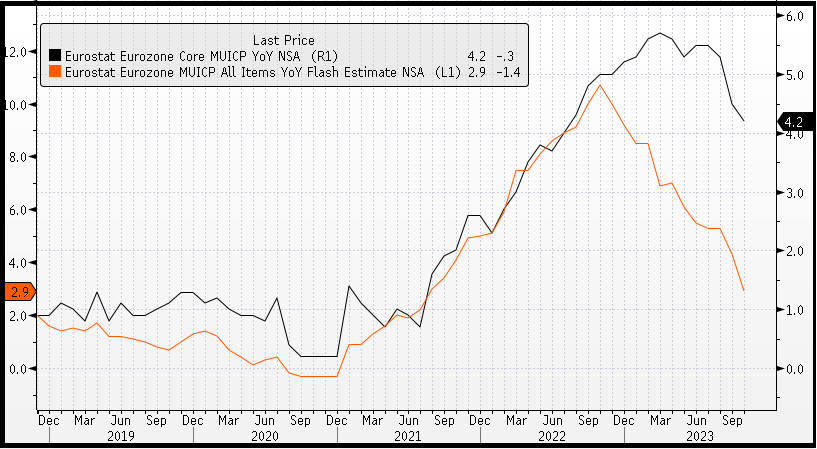
European equities closed higher on Tuesday following softer-than-forecast inflation data, which should relieve pressure on the ECB. Over the month of October, headline prices rose 0.1%, well below the 0.3% forecast, and rose 2.9% over the year vs 3.1% forecast. Meanwhile, core inflation was in line with estimates of 4.2% over the 12 months. Eurozone economic growth was weaker than expected, with the economy contracting -0.1% over the third quarter vs estimates to be unchanged, expanding at a weak 0.1% over the year. The Euro Stoxx 600 rose 0.59% along with the DAX 0.64% and CAC 0.89% while the FTSE100 was -0.08% lower. The Euro was -0.38% weaker at 1.0575 following the data, along with the Pound which declined -0.14% to 1.2153.
Eurozone Inflation (YoY %)
Australia
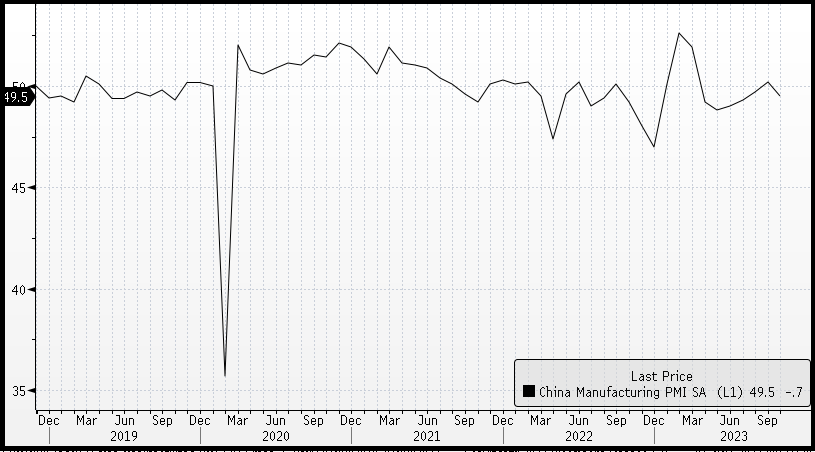
The local market is expected to open higher today, with ASX futures up 0.52% to 6,818. The index rose marginally on Tuesday, up just 0.11% with real estate the top performing sector, up 1.06% after higher-than-expected housing credit data, also likely contributing to the bounce is the recent slump in property stocks on expectations for monetary policy to remain tighter for longer. For the month of September, housing credit rose 0.5% vs 0.3% forecast, up 4.9% from a year earlier. Further housing data will be released today in the form of building approvals. Materials was the biggest underperformer, down -1.08% following Chinese PMI data which showed manufacturing declined to contractionary levels in October at 49.5, missing estimates to remain unchanged at 50.2. Sayona Mining plummeted -7.41%, Pilbara Minerals declined -3.93%, BHP receded -1.35% and RIO fell -0.61%.
Chinese Manufacturing PMI (MoM)
Commodities
Oil prices receded with WTI and Brent crude declining by -1.28% and -1.16% to $81.26 and $85.34 respectively. Precious metals saw their prices decline, spot gold receded by -0.56% to $1,985, while spot silver sank by -2.04% to $22.86. In industrial metals, copper shed -0.16% to $365.25 while SGX Iron Ore fell -0.14% to $121.55. The price of bitcoin was up by 0.8% to $34,648.
Economic Calendar
1st November 2023
New Zealand Employment (QoQ Q3) 08:45
Australian Building Permits (MoM Sep) 11:30
US ADP Employment (MoM Oct) 23:15
US ISM PMI (MoM Oct) 01:00
FOMC Rate Decision 05:00
This article was written by James Woods, Portfolio Manager, Rivkin Securities Pty Ltd. Enquiries can be made via [email protected] or by phoning +612 8302 3632.

